

The Retirement Confusion
Bunny sat with a heavy sigh, looking at his cup of tea, “Uncle, I’ve spent decades working, saving, worrying… and now that retirement is here, I feel more lost than ever. Fixed deposits barely cover inflation, and the stock market feels like gambling to me.
I just want a monthly pension. But private job people don’t get pensions, Uncle!”
His voice cracked between frustration and fear - the kind of fear that comes when you realise your steady salary days are over, but the bills never stop arriving.
Enter the Guide, Investing Uncle
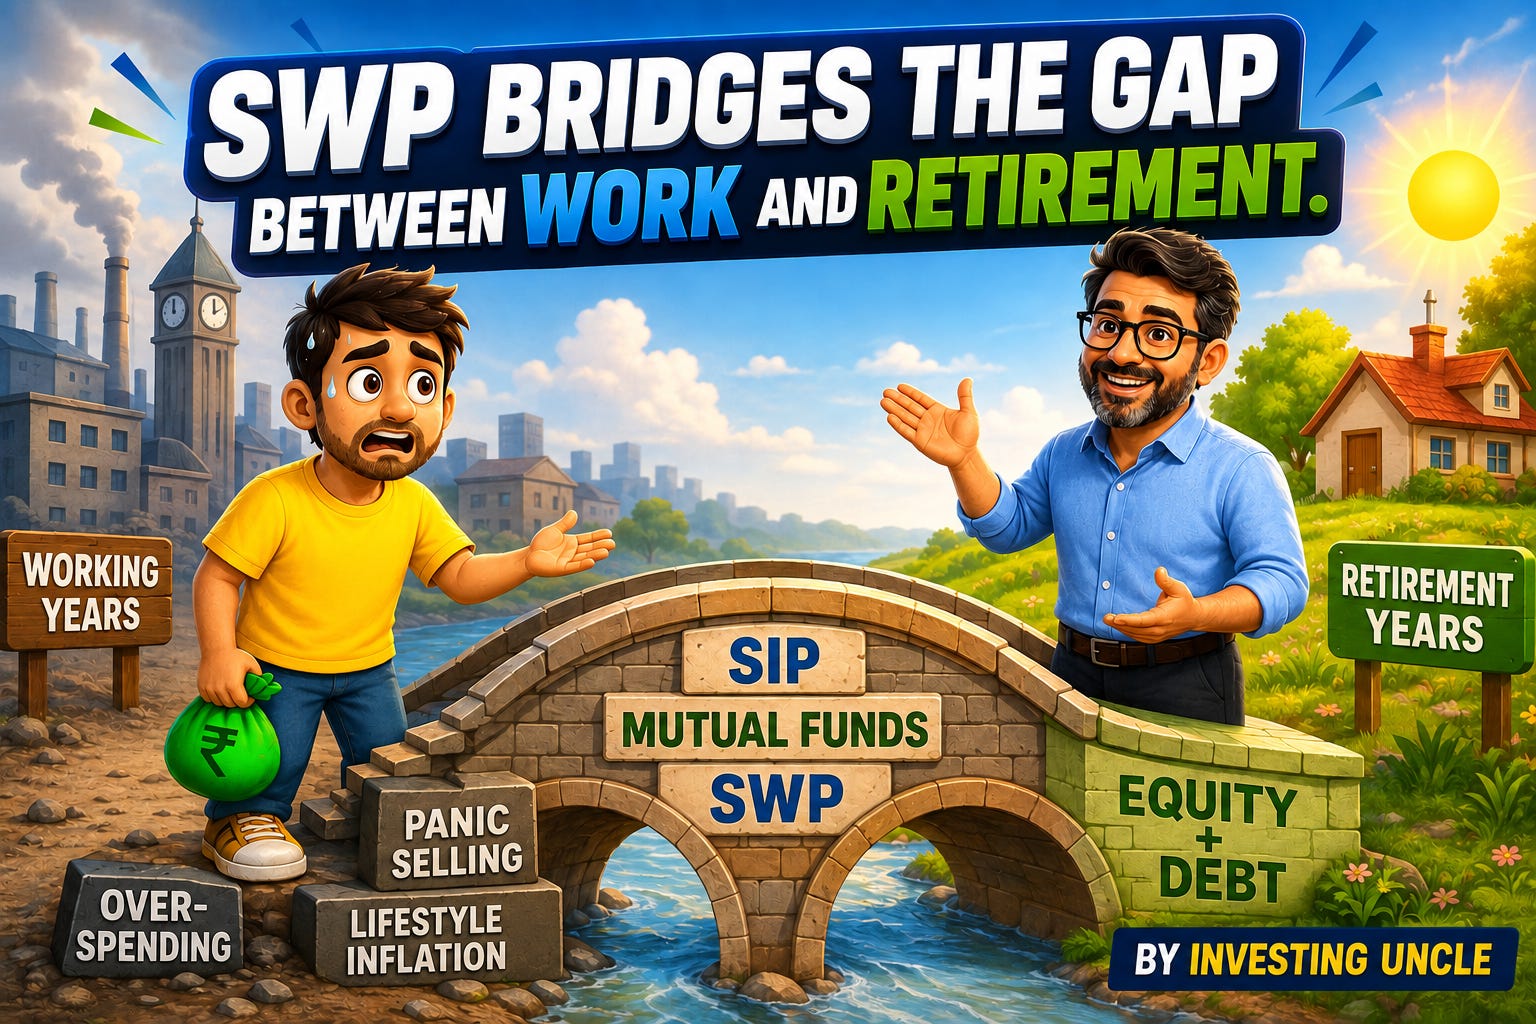
I smiled. “Bunny, you don’t need to depend on the government pension system. You can create your own pension from your mutual fund investments. And that’s called a Systematic Withdrawal Plan (SWP).”
Bunny blinked. “Systematic… What Plan? I’ve never heard about this Systematic… Which Plan..?”
“Think of it simply as the reverse of SIP:
SIP = You Invest money every month (Buy Units of Mutual Funds).
SWP = You Withdraw money every month (Sell Units of Mutual Funds).
That’s it. People make it sound complicated, but it’s really just this.”
The Problem - Bunny’s Worry
Bunny: “But Uncle, what if my money finishes too quickly? What if the market crashes? And what about taxes?”
Uncle Smile
“Relax, Bunny. Let me explain SWP properly. Once you understand it, you’ll never look at retirement the same way.”
What is SWP?
A facility to withdraw a fixed amount regularly (monthly/quarterly/yearly) from your mutual fund investments.
Works like your own personal pension.
Each withdrawal = the fund redeems a few units and gives you cash.
Remaining units stay invested and keep growing.
Why Use SWP as a Retirement Pension?
Steady Income: Feels like a salary every month.
Growth Continues: Your money is still invested, not lying idle.
Beats Inflation: Equity funds in the mix help you keep up with rising costs.
Tax-Friendly: More efficient than fixed deposit interest (capital gains taxation is better).
Equity Mutual Funds = Growth Engine
Equity funds = higher long-term growth.
Ideal for beating inflation during retirement years.
You withdraw small amounts, while the rest keeps compounding.
Best suited for a long retirement horizon (15–20+ years).
Risk: Market ups and downs - so don’t depend only on equities.
Debt Mutual Funds = Stability Engine
Safer than equities, with more stable returns.
Great for covering near-term expenses (3-5 years into the Retirement).
Provides smoother cash flow during stock market volatility.
Works as a buffer - when equities fall, you withdraw from debt.
The Winning Combo = ‘Equity + Debt’ Mutual Funds (Investing Uncle’s Personal Plan)
Here’s the recipe for a balanced retirement pension:
Step 1: Keep minimum 5 years of expenses in Debt Funds (your safety bucket).
Step 2: Keep the rest in Equity Funds (your growth bucket).
Step 3: Take monthly income first from the Debt bucket.
Step 4: Every 5 years, you may consider refilling the Debt bucket by moving profits from Equity Funds, via Systematic-Transfer-Plan. (Uncle will explain STP in the future blogs)
Result = Safety + Growth + Steady Pension.
Just an Example (and not recommendation or a Retirement Plan)
Imagine Bunny retires with Rs.2 Crore Corpus.
70% in Equity MF = Rs.1.4 Crore
30% in Debt MF = Rs.60 Lakh
Monthly expense = Rs.60,000.
Debt bucket provides Rs.60,000/month for 5 years = Rs.36 Lakh.
Equity + Debt keeps growing.
After 5 years - transfer equity profits into Debt bucket again.
This cycle can last many years, providing Bunny with a reliable retirement pension.
Note: In SWP, only capital gains on redeemed units are taxed.
Practical Tips for New Retirees
Never keep 100% in equity or 100% in debt - always balance.
Review SWP amount every year (inflation adjustment).
Maintain a separate emergency fund (6-12 months of expenses).
Prefer Direct Plans + Low-cost Index Funds.
Monthly SWP gives stability (like a pension).
**Always Consult a financial adviser for fund and tax planning.**
Risks You Should Know
Capital Erosion: If you withdraw more than what your funds earn, your corpus will shrink.
Market Volatility: A sudden crash affects equities, but the Debt bucket protects your monthly flow.
Bunny’s Transformation and Big Relief
Bunny leaned back in his chair. “Uncle, I always thought only government employees got pensions. Now I understand - even I can create my own pension plan. And it’s tax-efficient, inflation-proof, and steady.”
I nodded. “Exactly. Retirement is like chess. SWP is your queen - it gives you power, safety, and growth, all in one move.”
Our Reader = Real Hero
If Bunny can do this, so can you, My Dear Reader.
Even if you’re starting late in your 40s, don’t panic. I’ve explained that in my earlier blog…
How to Catch Up on Retirement Savings After 40 (Without Panic)
…Combine that wisdom with SWP, and your pension is sorted.
“Don’t wait for the government to give you a pension - with SWP, you can become your own pension provider.”
Treat Uncle with a Cup of Tea
If this blog saved you from a weak retirement, maybe treat Uncle with a cup of tea. If not, remember: even karma compounds over time.
Did this blog help you understand how to use SWP for retirement as a pension? Share your thoughts in the comments, and subscribe so you never miss the next tea-time lesson.
See you Next Sunday at 09:15 AM.
Disclaimer: Mutual fund investments are subject to market risks, read all scheme related documents carefully before investing. The past performance of the mutual funds is not necessarily indicative of future performance of the schemes. Investors are requested to review the prospectus carefully and obtain expert professional advice with regard to specific legal, tax and financial implications of the investment/participation. This blog/Website is for Educational purpose only. Any reference should not be treated as any form of Financial Advice.
Any person referred to in this post is purely coincidental. The characters, names, and situations mentioned are for illustrative and educational purposes only and are not intended to represent any real individual.
‘Investing Uncle’ is NISM Series V-A Certified (Mutual Fund Distributor’s Certification Examination) conducted by National Institute of Securities Markets (NISM).
Investing Uncle is not SEBI/AMFI Registered.